Assumable Loans: The Hidden Opportunity Most Homebuyers Don't Know ExistsBy Mark Sewell, REALTOR® | eXp RealtyWhat Is an Assumable Loan?Imagine being able to buy a home and keep the seller's

Dated: July 9 2026
Views: 46
 Assumable Loans: The Hidden Opportunity Most Homebuyers Don't Know Exists
By Mark Sewell, REALTOR® | eXp Realty
Imagine being able to buy a home and keep the seller's incredibly low interest rate instead of getting today's higher market rates.
That's exactly what an assumable loan allows.
Instead of applying for a brand-new mortgage at current interest rates, qualified buyers can "assume" or take over the seller's existing mortgage, including the remaining balance, interest rate, and loan terms.
With mortgage rates much higher than they were just a few years ago, assumable loans have become one of the biggest opportunities in today's real estate market.
Between 2020 and 2022, millions of homeowners locked in mortgage rates between 2% and 4%.
Today, many buyers are financing homes at rates that are significantly higher.
That difference can mean hundreds—or even thousands—of dollars in monthly savings.
For many buyers, an assumable loan can make the difference between comfortably affording a home and being priced out of the market.
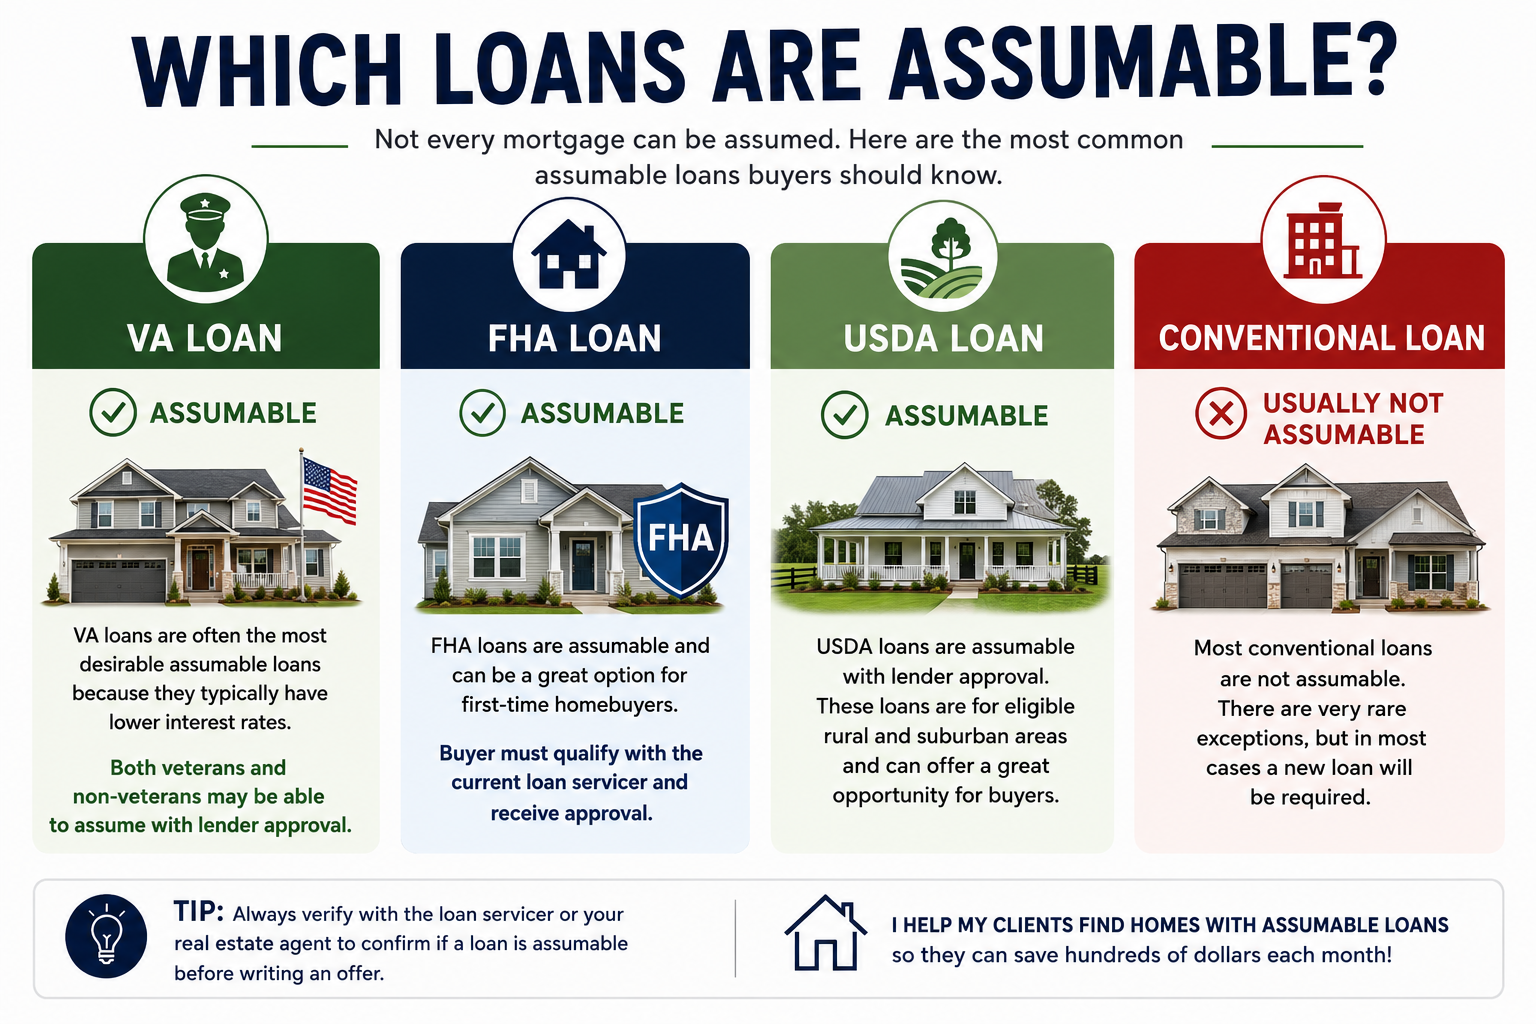
Not every mortgage can be assumed.
The most common assumable loans include:
VA Loans
FHA Loans
USDA Loans
Most conventional loans are not assumable.
One of the first things I do for my clients is identify which homes actually qualify before they spend time looking at properties that won't work.
Let's compare two buyers purchasing the same home.
Buyer A
Purchases with today's market interest rate.
Buyer B
Assumes the seller's existing 2.75% mortgage.
Both own the exact same house.
The buyer with the assumable loan could save hundreds of dollars every month—and potentially tens or even hundreds of thousands of dollars over the life of the loan.
That's money that stays in your pocket instead of going toward interest.
One of the biggest misconceptions about assumable loans is that buyers only need a standard down payment.
That's not always true.
When assuming a loan, you're taking over only the seller's remaining loan balance.
If the purchase price is higher than that balance, the buyer must cover the difference.
For example:
Purchase Price: $600,000
Remaining Assumable Loan: $450,000
Cash Gap: $150,000
That gap can be covered in several ways:
Cash from the buyer
A second mortgage
Home equity from another property
Gift funds (when allowed by the lender)
Every transaction is unique, which is why having the right lender and REALTOR® is so important.
Yes.
Many buyers use a second mortgage to help bridge the cash gap.
The first mortgage remains the seller's low-interest assumable loan.
The second loan finances part or all of the remaining difference.
This strategy often results in a much lower blended payment than financing the entire purchase at today's market rates.
Not necessarily.
One of the biggest myths is that only veterans can assume VA loans.
In many cases, non-veterans can also assume a VA loan if they meet the lender's qualification requirements.
However, there are important considerations involving the seller's VA entitlement that should be discussed before moving forward.
Every situation is different, and understanding these details can protect both the buyer and seller.
Just because a loan is assumable doesn't mean everyone automatically qualifies.
Buyers still need to meet the lender's approval requirements, which typically include:
Credit qualification
Income verification
Debt-to-income guidelines
Underwriting approval
The approval process is similar to obtaining a mortgage, but you're qualifying to take over an existing loan instead of creating a new one.
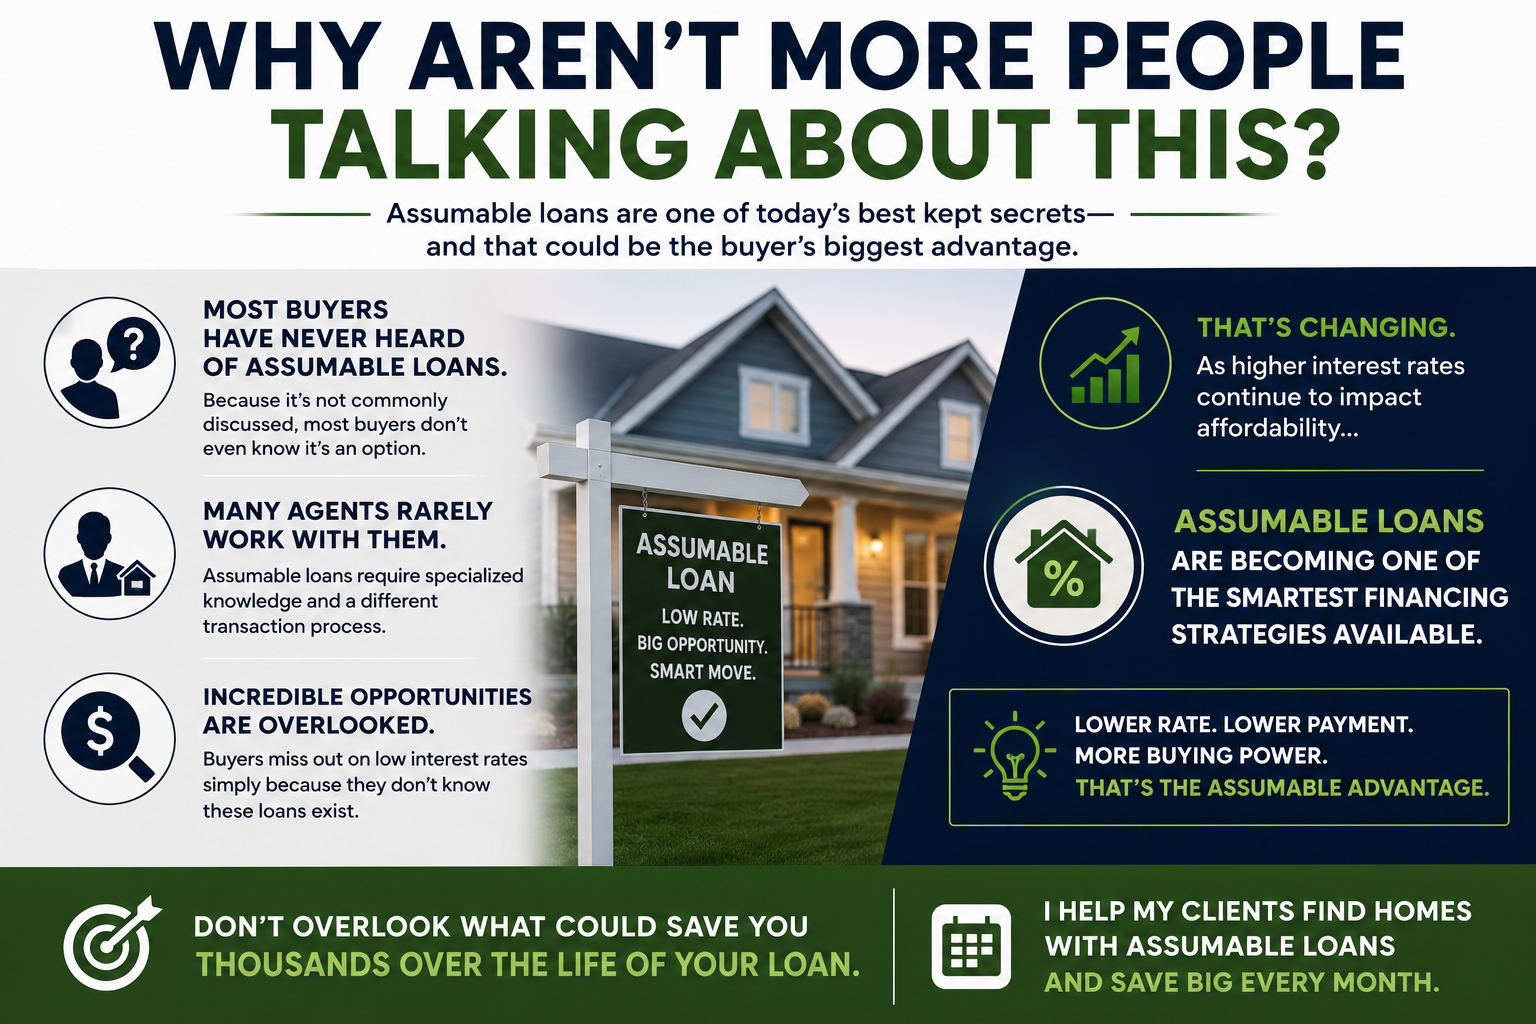
Most buyers have never heard of assumable loans.
Many real estate agents rarely work with them because they require specialized knowledge and a different transaction process.
As a result, incredible opportunities are often overlooked simply because buyers don't know they exist.
That's changing.
As higher interest rates continue to impact affordability, assumable loans are becoming one of the smartest financing strategies available.
Finding assumable loans isn't as simple as searching any real estate website.
You need someone who knows how to identify qualifying properties, explain the financing strategy, coordinate with lenders familiar with assumptions, and guide you through the process from start to finish.
That's exactly what I help my clients do.
Whether you're buying your first home, moving up, or looking for an investment property, assumable loans may open doors that traditional financing simply can't.
Assumable loans aren't a loophole—they're one of the most underutilized opportunities in today's housing market.
The right property with the right existing loan could save you substantial money over the life of your mortgage while making homeownership more affordable today.
If you're curious whether an assumable loan could work for you, I'd be happy to walk you through the process and show you available opportunities in the Sacramento area.
Knowledge is power—and in today's market, understanding assumable loans could give you a significant advantage over other buyers.
If you're buying or selling a home in the Sacramento region and want to explore assumable loan opportunities, let's connect.
I specialize in helping buyers identify homes with assumable financing and guiding them through every step of the process.
Your next home may already have an incredible interest rate waiting for you.
I’m Mark Sewell, a Sacramento-area Realtor® with eXp Realty, serving buyers, sellers, and investors throughout Sacramento, Roseville, Rocklin, Folsom, and Placer County.I help clients make s....
Assumable Loans: The Hidden Opportunity Most Homebuyers Don't Know ExistsBy Mark Sewell, REALTOR® | eXp RealtyWhat Is an Assumable Loan?Imagine being able to buy a home and keep the seller's
Best New Construction Communities in Sacramento, CA: Where to Buy a New Home in 2026Buying a new construction home in Sacramento can be exciting, but it can also be overwhelming. Between builder
Sacramento & Placer County New Construction Expert | Northern California Realtor®Buying New Construction the Right WayNew construction in Northern California isn’t as simple as walking
FHA 203(k) Loans: How to Buy and Renovate a Fixer-Upper in the Sacramento AreaMany homebuyers believe they need to find a perfect, move-in-ready home when purchasing a property. But what if you
Should you require assistance in navigating our website or searching for real estate, please contact our offices at 916-318-3487.
CA License # 02011293

 All measurements and all calculations of area are approximate. Information provided by Seller/Other sources, not verified by Broker. All interested persons should independently verify accuracy of information. Provided properties may or may not be listed by the office/agent presenting the information. Data maintained by MetroList© may not reflect all real estate activity in the market.
All real estate content on this site is subject to the Federal Fair Housing Act of 1968, as amended, which makes it illegal to advertise any preference, limitation or discrimination because of race, color, religion, sex, handicap, family status or national origin or an intention to make any such preference, limitation or discrimination.
MetroList CA data last updated: September 25, 2026 7:28 PM UTC Terms of Use.
Vendor data provided by Inside Real Estate, LLC.
 All data, photos, visualizations, and information regarding a property, including the property's compliance with state and local legal requirements and all measurements and calculations of area, have been obtained from various sources, and may include such material that has been generated by use of artificial intelligence. Such information and material have not been and will not be verified for accuracy by the listing broker or the multiple listing service, and are not guaranteed as complete, accurate or reliable. Such information and material should be independently reviewed and verified for accuracy. This information and material are intended for the personal use of consumers and may not be used for any purpose other than to identify prospective properties consumers may be interested in purchasing. Copyright ©2026 Bay Area Real Estate Information Services, Inc. All Rights Reserved.
